What Happens During a Free Credit Card Processing Audit?
A processing audit is a closer look at one statement. Here's exactly what we review, what you'll walk away with, and what it isn't.
"Free audit" can sound like a sales call with a nicer name. So here's exactly what happens, what you get out of it, and what it doesn't promise.
What you'll need
One recent merchant statement. That's usually enough. If you have a separate equipment lease or software bill, that helps too.
We don't need customer card numbers, security codes, or login credentials. Statement formats vary, so check yours for sensitive information before sharing it. Ask how to submit it securely, and redact customer payment details and any information not needed for the review.
What we review
- Total processing volume: how much you ran through cards that month
- Total fees: everything you paid, including anything billed outside the statement
- Effective processing rate: fees as a share of sales, your real rate
- Pricing structure: flat, tiered, or interchange-plus, and what that means for you
- Processor markup: the part of your cost your processor controls
- Additional statement charges: monthly, yearly, PCI, and other fees
- Areas worth looking into: anything that seems high, unclear, or avoidable
- Contract considerations: term, renewal, and what leaving would cost
How the call works
It's a short call, about 15 minutes. We go through your statement together and explain what each part means. You can ask anything.
At the end, you'll know your effective rate, which of your fees come from the card networks and which from your processor, and whether anything looks worth questioning.
What an audit isn't
It isn't a guarantee of savings. Some businesses are already on fair pricing. If that's you, we'll say so.
It isn't a commitment. You don't have to switch anything. You can take what you learn and call your current processor yourself. Some owners do exactly that.
It isn't a contract. Nothing is signed during the call.
We show you the numbers. You decide whether anything needs to change.
Who it's for
Bring these questions to the call
- What did I pay in total, and does that include separately billed payment costs?
- Which charges can my processor change, and which are pass-through costs?
- If you're proposing an alternative, what would the same month's transactions have cost, including recurring fees?
- What assumptions could change that estimate—card mix, transaction count, annual fees, or promotional pricing?
- Would cancellation, equipment, software, or funding terms offset the potential benefit?
How to read a potential savings figure
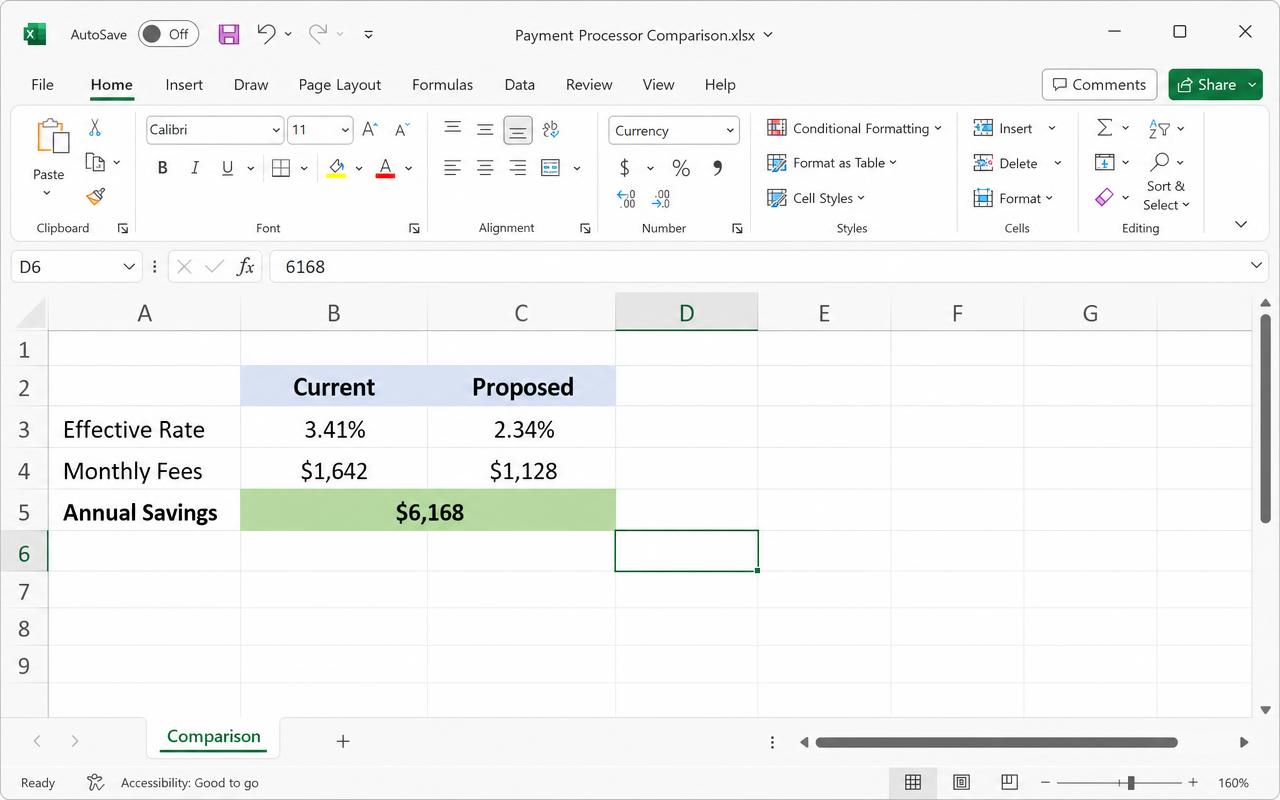
Illustrative comparison—not a promised result
The right question isn't "Is that rate lower?" It's "Are both totals based on the same sales, transaction count, services, and time period?" If something can't be verified from your statement, treat the comparison as provisional and ask what additional information is needed.
What happens after the review?
You decide whether to investigate further. You can ask your current processor about the findings, consider a documented alternative, or leave your setup alone. If you consider switching, review the full pricing and agreements separately; a statement review is not a substitute for checking cancellation, equipment, and integration details.
Audits are most useful for businesses processing $15,000 or more a month in card sales. At that level, even small differences in fees add up to real money over a year.
If you'd like to do some of the work first, start with the seven warning signs or find your effective rate. When you're ready, you can request your free audit here.