7 Questions to Ask Before Choosing a Credit Card Processor
The lowest quoted rate doesn't always win. These seven questions help you compare processors on what you'll actually pay and live with.
Comparing processors is harder than it should be. Everyone leads with a rate, and the rates are hard to compare because they mean different things on different plans.
These seven questions get you past the sales pitch. Ask every processor the same ones, write down the answers, and compare side by side.
1. What kind of pricing plan is this?
Flat rate, tiered, or interchange-plus? Each one works differently, and it changes what the quoted number covers. If you're not sure what these mean, read Why Your Quoted Rate Isn't What You Pay first.
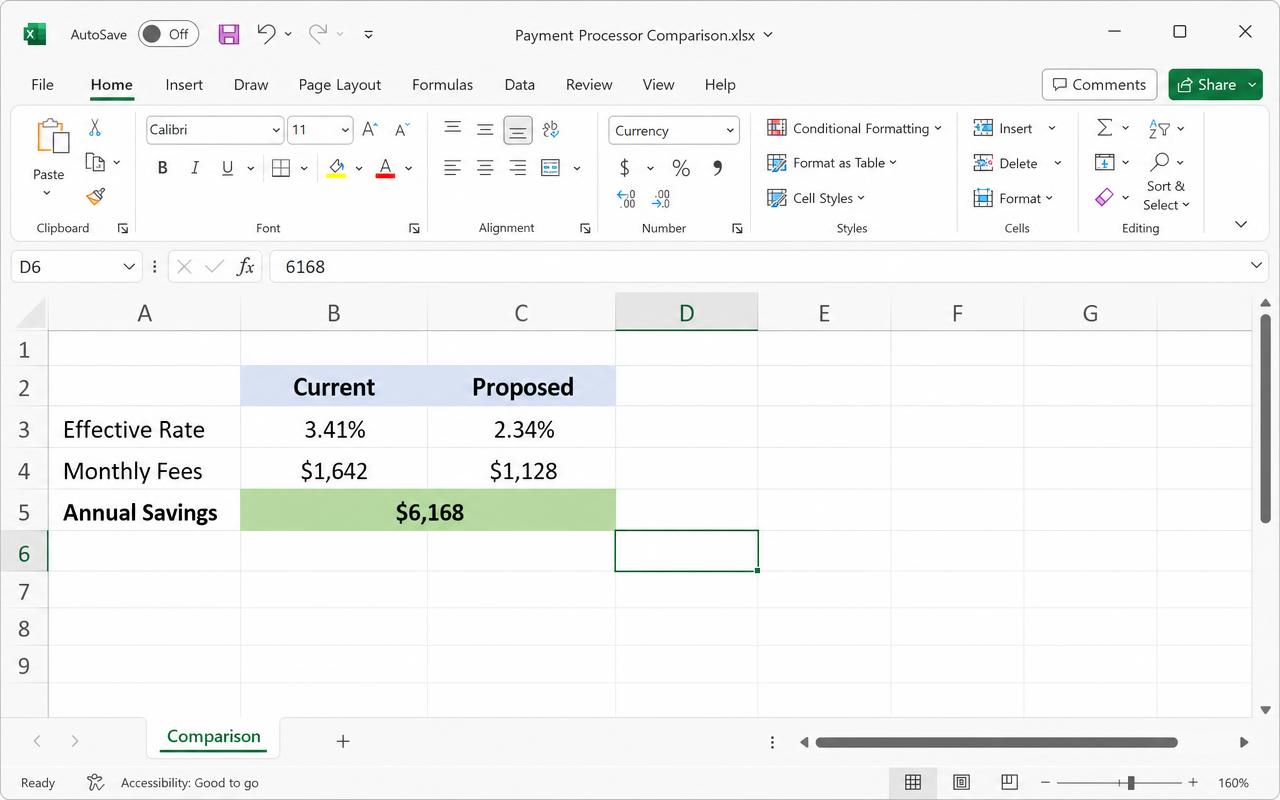
2. Based on my actual statement, what would I have paid last month?
This is the most useful question on the list. Hand over a recent statement and ask for a total, in dollars, for that same month. It turns a confusing rate into a number you can compare to what you really paid.
3. What are all the fees, besides the rate?
Ask for a written list. Monthly fees, yearly fees, PCI fees, statement fees, gateway fees, chargeback fees, batch fees. If the list is long, ask what each one is for.
4. How long is the contract, and does it renew automatically?
Some contracts run three years and renew on their own unless you cancel within a short window. Know the term and the renewal rules before you sign.
5. What does it cost to leave?
Ask about the early termination fee in plain terms. Is it a flat amount? Is it based on fees you would have paid? Is there any way to leave without it? This is the question people most often skip and most often regret.
6. Will my equipment and software work?
Ask whether your current terminal, point-of-sale system, and online store will work. If you need new equipment, ask whether you can buy it outright instead of leasing, and what each option costs over time.
7. Who do I call when something breaks?
Card machines tend to stop working at the worst moment. Ask how support works. Is it a phone line with a person, or a ticket system? What hours? Will you have one main contact who knows your account?
A simple comparison sheet
| Question | Processor A | Processor B |
|---|---|---|
| Pricing plan | ||
| Total cost on last month's statement | ||
| Monthly and yearly fees | ||
| Contract length / auto-renew | ||
| Cost to leave | ||
| Equipment and software fit | ||
| Support |
Compare total dollars on your own statement, not quoted rates. Then compare the contract and support, because you'll live with those for years.
What a useful answer actually looks like
| If they say… | Ask for… |
|---|---|
| You'll save money | A written dollar estimate on your actual statement, with the assumptions and exclusions. |
| There's no contract | The processing agreement, cancellation requirements, and any separate equipment or software terms. |
| Your terminal should work | Compatibility confirmation for the exact model and your point-of-sale integration. |
| We have great support | Support hours, after-hours contacts, and the escalation process for missing deposits. |
| The equipment is free | Ownership, return requirements, replacement costs, and any commitment attached to it. |
Ask a deposit question, too
"If I close a batch on Friday evening, when should I expect the deposit? What are the cutoff times, weekend rules, and circumstances that could lead to a reserve or funding hold?" A low fee isn't much comfort if the funding arrangement doesn't suit your cash flow. Get the applicable terms, not an unconditional promise of next-day money.
Before you sign anything
- Send each provider the same statement and describe the same payment setup. Remove customer payment data and use the provider's agreed secure method.
- Request the full fee schedule, processing agreement, and any separate lease or software agreement—not just the proposal page.
- Check the first-year total and the ongoing total, including what happens when promotions expire.
- Resolve missing answers in writing. If an important promise isn't reflected in the documents, don't assume it will apply.
Already with a processor and not sure if it's worth the trouble? Negotiate or Switch? covers that decision.
Further reading
Read the the FTC's guidance on credit card processing deals for background on checking sales claims and equipment commitments. Then compare the specific written agreements in front of you.